Micron Technology closed its fiscal year with a record quarter that showed how quickly artificial-intelligence investment is reshaping the memory-chip business. The company reported fiscal fourth-quarter revenue of $54.23 billion, up from $41.46 billion in the prior quarter and $11.32 billion a year earlier. The scale of that increase put the results above Wall Street expectations and shifted attention from whether AI demand is still growing to how long suppliers can sustain the pace. The year-over-year comparison also shows how abruptly spending has accelerated.
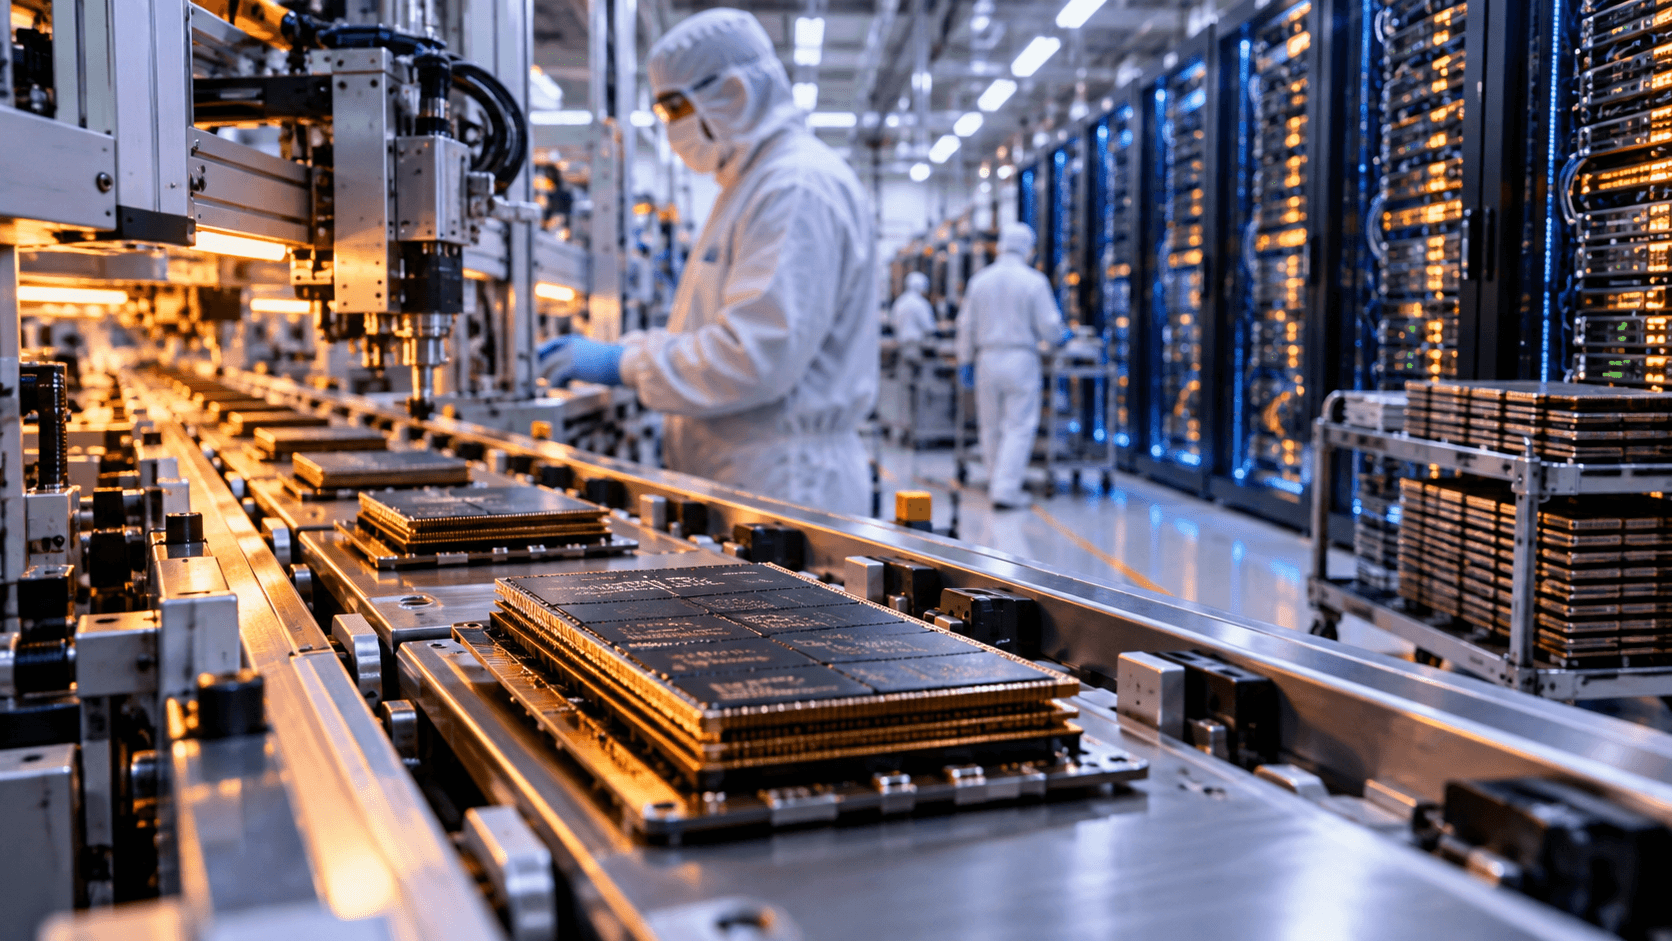
The next-quarter outlook was also stronger than analysts had anticipated. Micron forecast revenue of $60 billion to $63 billion, while Reuters reported a market estimate below that range. The company said customer commitments under long-term supply agreements had reached $32 billion, another sign that large buyers are trying to secure access to scarce memory capacity. Demand for high-bandwidth memory and other components used in AI servers has become the central engine of Micron’s expansion, even as the company still serves personal-computer, smartphone and industrial markets.
A Polymarket event tied to Micron’s share price remained active after the earnings release and drew more than $7,300 in activity over the previous 24 hours. Its most liquid open outcome assigned about a 76% chance that Micron shares would touch $1,110 by the end of the week, up roughly 11 percentage points in one day. That contract captures traders’ immediate reaction to the report, but it is not a forecast from Micron and does not establish where the stock will close. Short-dated prices can move sharply as investors digest guidance, conference-call details and broader financial conditions.
The results also raise a harder operational question. Producing more advanced memory requires heavy capital spending, long construction schedules and close coordination with customers that are building AI data centers. Strong demand can support pricing and margins, but it also creates pressure to add capacity without overshooting a cycle that has historically been volatile. Micron’s outlook suggests management expects tight conditions to persist into fiscal 2027, yet the durability of that view will depend on cloud companies continuing to fund new systems and on competing suppliers exercising similar discipline. Manufacturers must decide years in advance how much equipment and factory space future demand will justify.
Investors will now look beyond the headline revenue beat to shipment schedules, supply-deal pricing and the pace at which new capacity comes online. The company’s next quarterly report should offer clearer evidence on whether commitments are converting into deliveries and cash flow at the rate management expects. For customers, the immediate issue is access to the memory required for increasingly large AI systems. For Micron, the challenge is to turn an extraordinary surge in demand into durable earnings without allowing today’s shortage to become tomorrow’s excess supply.