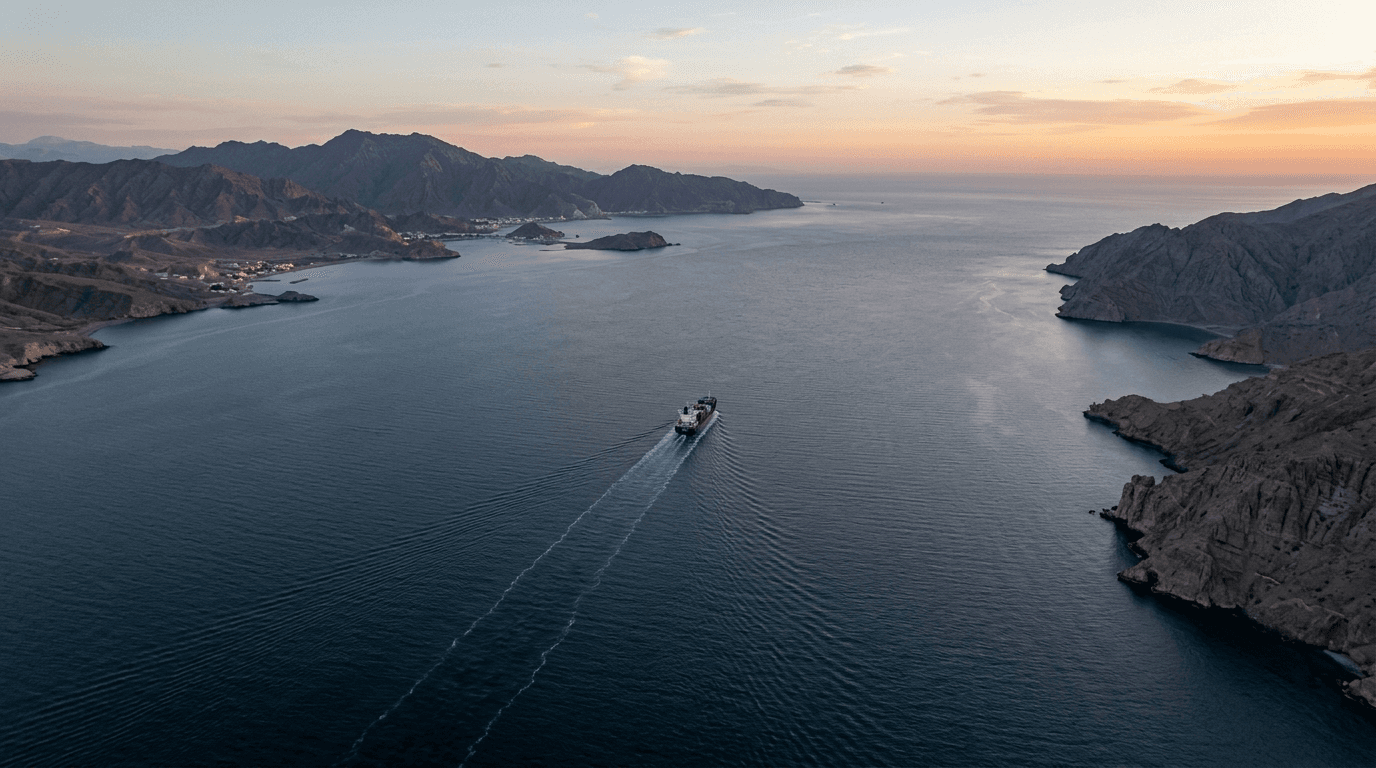
The Strait of Hormuz is an important route for global energy flows, so a sustained return of commercial traffic could matter well beyond shipping companies. Before the conflict, the strait carried some 20% of the world’s oil and natural gas. NBC also reported that US gas prices rose during the conflict by more than 40%. The central question is whether traffic can recover, not how a contract performs. The available reporting documents severe disruption, but it does not show whether a low recent reading will persist or give a reliable path from that reading to an average for the rest of the year.
Kalshi’s market puts the chance that the seven-day moving average of transit calls clears the lowest listed threshold at 37% as of 7:43 a.m. ET on Sept. 28. The quoted threshold is above forty. Higher thresholds draw lower prices: the chance of exceeding fifty is 21%, while the chance of exceeding eighty is 4%. These prices describe what traders currently believe, not objective probabilities or forecasts. The thresholds overlap rather than divide outcomes into mutually exclusive possibilities, so they do not provide a complete distribution or a single expected traffic level. The available market figures also show that trading was limited on most thresholds, which counsels against treating every quoted price as a broad consensus.
Recent reporting supports the view that traffic has been severely disrupted. A brief says PortWatch recorded 1 transit on 2026-09-20. NBC’s update likewise said traffic remained far below its pre-war level of hundred-plus ships a day. That reading is evidence about one date, not a measurement of the full-period average and not a forecast for the remaining months. The market concerns a seven-day moving average during a specified period; the brief’s cited observation is a single-day count. The two measures answer different questions. Neither the observation nor the market prices establish a reliable path from current disruption to a particular average.
The reported count also has a limitation. NBC cautions that the exact numbers may be higher. That means the observed traffic could understate actual transits, although the packet does not quantify any gap between tracked and actual movement. The brief notes that QatarEnergy-linked vessel transits resumed in the last week. It describes this as limited activity, which does not establish that shipping more broadly has returned. A small sign of movement and continued severe disruption can coexist; the available evidence does not show that the resumed transits mark a lasting change in overall traffic.
The latest reporting also describes a setback to a proposed reopening effort, including the seven-day plan. That context underscores why the eventual average remains uncertain: the sources report both very low traffic and limited vessel activity, but they do not establish whether either condition will persist. The market offers a snapshot of trader belief across several thresholds, not evidence that a reopening is imminent or that traffic will reach any one level. A clearer picture would require sustained evidence of transits over time, interpreted with the tracking caveat in mind. Until then, a very low count on one date cannot settle how much traffic will pass through the strait on average during the market’s period.